Suzlon's Profit Did Not Really Fall 69%: What Actually Went Wrong
Suzlon's Q2 profit fell 69%, but a one-off ₹891 crore tax credit in the year-ago quarter explains most of it. The real issue is margins at 14.7%, down from 18.6%.
- Published
- Reading time
- 8 minutes
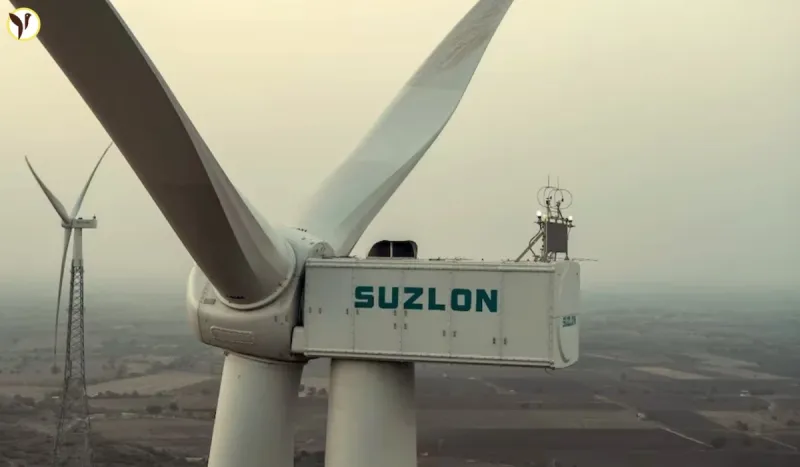
Suzlon Energy shares fell as much as 9.73% to a 52-week low of ₹33.21 on Thursday after the company reported a 69% drop in quarterly profit. But the year-ago quarter contained a one-off ₹891 crore tax credit. Strip that out and profit was roughly flat. The real problem is margins, which fell to 14.7% from 18.6%.
If you own this stock, or you are trying to work out what just happened to it, the 69% figure in every headline is the least useful number in the release. Here is what the quarter actually showed.
What was reported
For the quarter ended September 2026, Suzlon reported:
- Revenue from operations of about ₹4,875 crore, up 26% from ₹3,871 crore a year earlier
- Consolidated net profit of ₹394 crore, down 69% from ₹1,279 crore
- EBITDA of ₹719 crore, against ₹721 crore a year earlier
- EBITDA margin of 14.7%, down from 18.6%
- Net worth above ₹10,000 crore for the first time
Against what analysts had pencilled in, the result splits cleanly in two. Brokerages had expected revenue of ₹4,670 crore to ₹4,815 crore, so revenue beat the whole range. They had expected net profit of ₹459 crore to ₹578 crore and EBITDA of ₹770 crore to ₹784 crore, so both missed, profit by a wide margin.
A company that sells more than expected and earns less than expected is telling you something specific. It is worth understanding what.
The ₹891 crore nobody is mentioning
The 69% fall is arithmetically correct and substantively misleading, and the company said so itself.
Chief Financial Officer Rahul Jain pointed out that the year-ago quarter included a deferred tax asset creation of ₹891 crore.
A deferred tax asset is, in plain terms, a credit a company books when it expects to pay less tax in future usually because it has accumulated past losses it can set against future profits. When a company becomes confident enough that those profits will arrive, accounting rules let it recognise that future benefit now. It flows through the profit line as a gain. No cash comes in. It happens once.
That is what inflated the September 2025 quarter. Take the ₹891 crore out of the ₹1,279 crore and the comparable figure is roughly ₹388 crore. This quarter's ₹394 crore sits just above it.
So the honest version of the profit line is not "profit collapsed by two thirds." It is "profit was broadly flat, against a quarter that had been flattered by a one-off."
This is worth knowing beyond Suzlon. One-off tax credits, asset sale gains and write-backs distort year-on-year comparisons constantly, in both directions, and headlines rarely adjust for them. When a profit figure moves violently and revenue does not, a one-off is the first thing to look for and it is usually disclosed, often in the company's own commentary.
Now the part that is actually a problem
Having dismissed the scary number, here is the unscary one that matters.
Revenue grew 26%. EBITDA did not grow at all ₹719 crore against ₹721 crore. Operating margin fell from 18.6% to 14.7%, a drop of about 390 basis points.
That is the whole story of the quarter. Suzlon sold meaningfully more and converted none of it into additional operating profit.
Nuvama Institutional Equities attributed part of the squeeze to specific causes, saying margin weakness "reflects forex/commodity headwinds (50 bps) and Suzlon 2.0 costs (100 bps)" the latter referring to the company's restructuring programme. That accounts for about 150 of the roughly 390 basis points. The remainder has not been publicly broken down, and it would be guesswork to attribute it here.
Nuvama also flagged that "cash conversion stayed weak," which is the second real concern and the less visible one. Reported profit is an accounting outcome; cash conversion is whether the business turns that into money in the bank. A company growing revenue fast while converting it poorly into cash is running a working-capital problem, and that shows up in borrowing before it shows up in profit.
The operational side was genuinely good
It would be a distortion in the other direction to present the quarter as a failure. On delivery, it was the opposite.
- Order book above 6 GW, with more than 1.5 GW of fresh orders in the first half of FY27
- Record Q2 deliveries of 710 MW, above the 660 to 665 MW brokerages had forecast
- 454 MW commissioned in the quarter and 723 MW across the first half, for customers including Juniper Green Energy, Aditya Birla Renewables, Zelestra and Brookfield Yanara
- EPC work now 38% of the order book, up from 22% in the first quarter of FY26, with a company target of 50% by FY28
- Public sector and commercial and industrial customers account for 78% of the order book
Chief Executive Ajay Kapur pointed to "record Q2 deliveries of 710 MW and commissioning of 454 MW."
So the demand is there, the execution improved, and the balance sheet strengthened. What did not happen is the margin coming through on any of it. That is a narrower criticism than the headlines suggest, and a harder one to fix quickly.
Four days, and a third off the targets
This part is less about Suzlon than about how to read what analysts publish, and it is worth your attention if you have ever bought a stock on a target price.
On Monday 26 October, with the stock at ₹36.77, Bloomberg data covering ten brokerages showed nine rating Suzlon a Buy, with targets implying anywhere from 25% to 100% upside. The published targets were:
| Brokerage | Target before results |
|---|---|
| Centrum Broking | ₹74 |
| Investec | ₹67 |
| UBS | ₹66 |
| Motilal Oswal | ₹65 |
| Anand Rathi | ₹65 |
| ICICI Securities | ₹65 |
| Axis Capital | ₹64 |
| Systematix | ₹63 |
| Ambit Capital | ₹59 |
| JM Financial | ₹46 |
| Nuvama (Hold) | ₹51 |
By Thursday, after the results, the revisions were these:
| Brokerage | Old | New | Note |
|---|---|---|---|
| UBS | ₹66 | ₹58 | |
| Investec | ₹67 | ₹56 | |
| ICICI Securities | ₹65 | ₹55 | |
| Ambit Capital | ₹59 | ₹55 | Said Q2 deliveries caught up and volume growth held |
| Axis Capital | ₹63 | ₹42 | Downgraded to Add from Buy |
| Nuvama | ₹51 | ₹41 | Hold; cut FY27 and FY28 EPS, moved to a 20x FY29 earnings basis plus a discounted cash flow value for the O&M business |
Business Today reported that at least five brokerages retained Buy ratings.
None of this means the analysts were being dishonest. Revising a view when new information arrives is exactly what they are supposed to do, and the information in this result was genuinely new nobody outside the company knew the margin would land at 14.7%.
But it does tell you something about what a target price is. It is a conditional estimate built on assumptions about the next several quarters, and it moves when those assumptions move. It is not a forecast of where the share price will go, and the gap between a target and the market price is not money waiting to be collected. A target cut by a third in four days is the clearest possible illustration of that, and it is a more useful takeaway than any individual number in the table.
Where the stock stands
Shares hit an intraday low of ₹33.21 on Thursday, down 9.73%, and traded around ₹33.55 later in the session. The previous close was ₹36.79, with market capitalisation around ₹50,574 crore.
The 52-week high is ₹61.45, set in November 2025, which puts the stock roughly 46% below its peak. It is down about 40% over six months.
Two SEBI-registered analysts gave short-term technical readings. AR Ramachandran of Tips2trades said Suzlon "is bearish and oversold on daily charts, with the next support at Rs 32.46," and put resistance at ₹36.10. Jigar S Patel, Senior Manager for Technical Research at Anand Rathi, said "the stock is expected to trade within the Rs 32-38 range in the short term."
What would actually settle this
The question this result leaves open is narrow and specific, which makes it easy to check next time rather than argue about now.
Did the margin compression come from things that pass foreign exchange moves, commodity prices, one-off restructuring costs or from something structural in what Suzlon is now selling and at what price? Nuvama's breakdown accounts for 150 basis points of roughly 390. The next quarterly result is where the rest becomes visible.
Three things in the Q3 release will answer it. Whether the EBITDA margin recovers from 14.7% or settles there. Whether cash conversion improves, which you will see in working capital and borrowings rather than in the profit line. And whether order intake holds above the roughly 750 MW a quarter pace implied by the first half, because the order book is the one part of this business that has not wobbled.
Until then, the honest position is that a company with a 6 GW order book and record deliveries has a margin problem it has only partly explained, and the people who follow it professionally have just marked down their estimates by up to a third while mostly keeping their ratings. Both of those things are true at once.
This article is for information only and is not investment advice. Figures are as reported by Suzlon Energy for the quarter ended September 2026 and as reported by the outlets cited; revenue has been reported variously as ₹4,869 crore, ₹4,875 crore and ₹4,908 crore across different sources. Brokerage targets and ratings are the views of those firms, not recommendations by this publication. Share prices are from Thursday 30 October 2026 and will have changed.
Questions readers ask
Why did Suzlon's share price fall if revenue beat estimates?
Because profitability missed. Revenue of about ₹4,875 crore came in above the ₹4,670–4,815 crore brokerages expected, but EBITDA of ₹719 crore fell short of the ₹770–784 crore forecast, and net profit of ₹394 crore was well below the ₹459–578 crore range. Operating margin fell to 14.7% from 18.6% a year earlier. The market was pricing the margin, not the sales.
Did Suzlon's profit really fall 69%?
Arithmetically yes, but the comparison is distorted. CFO Rahul Jain said the year-ago quarter included a one-off ₹891 crore deferred tax asset creation — a non-cash accounting credit recognised when a company expects to pay less tax in future. Excluding it, the comparable year-ago profit was about ₹388 crore, against ₹394 crore this quarter. On that basis profit was roughly flat rather than down two-thirds.
What is Suzlon's order book and how were deliveries?
The order book stands above 6 GW, with more than 1.5 GW of new orders in the first half of FY27. Q2 deliveries were a record 710 MW, above the 660–665 MW brokerages had forecast, and 454 MW was commissioned in the quarter. EPC work now makes up 38% of the order book, up from 22% in Q1 FY26, with the company targeting 50% by FY28. Public sector plus commercial and industrial customers account for 78% of the book.
What are brokerages saying about Suzlon after Q2?
Most cut their targets sharply. UBS moved from ₹66 to ₹58, Investec from ₹67 to ₹56, ICICI Securities from ₹65 to ₹55, Ambit from ₹59 to ₹55, Axis Capital from ₹63 to ₹42 with a downgrade to Add, and Nuvama from ₹51 to ₹41 with a Hold. Business Today reported at least five brokerages retained Buy ratings. Four days earlier, nine of ten covering brokerages had Buy ratings with targets implying 25–100% upside — a useful reminder that a target price is a conditional estimate that moves with new information, not a forecast of where a share price will go.
Where is Suzlon's share price now relative to its range?
Shares hit a 52-week low of ₹33.21 on 30 October 2026, falling as much as 9.73%, and traded around ₹33.55 later in the session against a previous close of ₹36.79. The 52-week high is ₹61.45, set in November 2025, leaving the stock roughly 46% below its peak and down about 40% over six months. Market capitalisation was around ₹50,574 crore. These figures change continuously check a live quote before acting on any of them.