Digital Arrest Scam: Will Banks Have To Pay You Back If You Lose Money?
The Supreme Court says banks should compensate digital arrest scam victims if bank negligence is proven. Know the latest update and what victims can do.
- Published
- Reading time
- 7 minutes
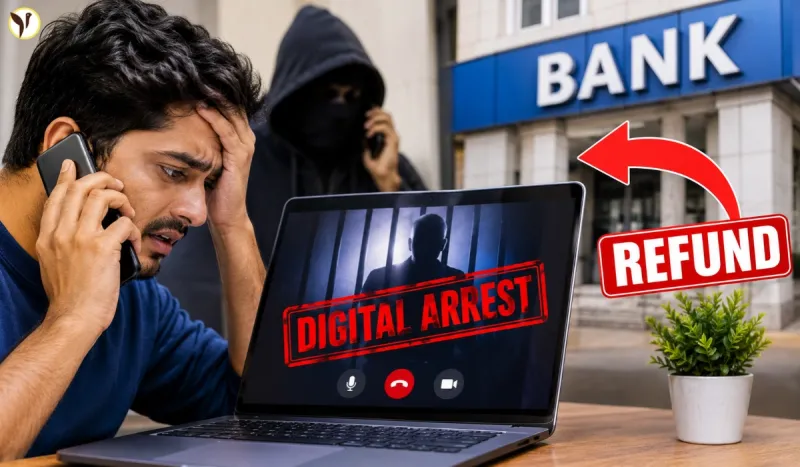
People who lose money in a digital arrest scam may get stronger protection under proposed banking rules. The Supreme Court has said that financial institutions should compensate victims when an investigation establishes that a bank's failure to perform its required checks contributed to the fraud.
The court's latest observation could become an important step in India's fight against cybercrime. However, it does not mean that every person who loses money to an online scam will automatically receive a full refund.
The Supreme Court wants the Reserve Bank of India (RBI) to examine a compensation mechanism as part of its proposed Know Your Customer (KYC) Amendment Directions, 2026. The court said compensation should cover at least the amount lost where the financial institution's failure of due diligence is found to have contributed to the crime.
So, will banks have to refund money lost in digital arrest scams? The answer will depend on the final rules and whether a bank's failure is established in a particular case.
What Did the Supreme Court Say on October 29?
A Supreme Court bench led by Chief Justice Surya Kant, along with Justices Joymalya Bagchi and V. Mohana, heard the matter concerning victims of digital arrest scams and forged documents.
The court said the proposed RBI framework should require financial institutions to compensate victims when a cyber fraud occurs because the institution failed to meet its due-diligence responsibilities.
It also asked the RBI to provide details of authorised financial institutions and the compensation measures being considered.
The court wants to examine the proposed RBI KYC Amendment Directions, 2026, which are expected to be notified by November 30, 2026, and implemented by December 31, 2026.
These are proposed regulatory measures. The final rules and their exact conditions will determine how the compensation system works.
Will Banks Refund All the Money Lost in a Digital Arrest Scam?
Not automatically. The Supreme Court's latest position focuses on cases where a bank or other financial institution is found to have failed in its due-diligence duties and that failure contributed to the fraud.
For example, a bank may need to answer questions if suspicious accounts were opened without proper checks, customer verification was inadequate, or unusual transactions were not handled according to applicable rules.
The court has emphasised that the proposed framework should provide compensation of at least the amount lost when such a failure is established.
However, the final mechanism is still being considered. A victim should not assume that filing a complaint alone guarantees a full refund.
What Is a Digital Arrest Scam?
A digital arrest scam is a form of cybercrime in which fraudsters pretend to be police officers, CBI officials, court representatives or officials from agencies such as the Enforcement Directorate.
They may tell a victim that their Aadhaar details, bank account, mobile number or parcel has been linked to a criminal investigation.
The scammers then use threats and pressure to make the person believe they are facing arrest or legal action. Some victims are kept on long video calls and told not to contact their family or anyone else.
Eventually, the fraudsters demand money, often describing it as a security deposit, verification payment or amount needed to settle a supposed case.
There is no legal process called “digital arrest” in India. Genuine law-enforcement agencies do not make criminal cases disappear by asking people to transfer money to private bank accounts.
Why Are Banks Being Asked to Take More Responsibility?
Money stolen in digital arrest scams is often transferred through multiple bank accounts. Some of these are known as mule accounts—accounts used to receive, hold or move money obtained through illegal activity.
If such accounts are opened or operated without proper checks, investigators may ask whether the relevant bank followed its KYC, anti-money-laundering and transaction-monitoring obligations.
The Supreme Court has called for stronger safeguards, including measures to identify unusual transactions and prevent suspicious transfers from moving further.
The aim is to improve prevention and recovery, rather than relying only on action after the money has disappeared.
What Preventive Measures Does the Court Want?
The court highlighted several measures that could help banks detect and stop suspicious activity.
These include:
- Temporarily suspending an unusual transaction when it sharply differs from the account holder's normal activity.
- Automatically alerting the appropriate authorities about suspicious transactions.
- Carrying out physical verification where needed to check whether a transaction is genuine.
- Informing nearby police stations when a customer may be under pressure from a digital arrest scam.
- Improving monitoring of mule accounts and strengthening customer verification.
The precise requirements will depend on the final regulatory directions and how they are implemented by banks and other financial institutions.
A Previous Case Shows Why Bank Checks Matter
In a separate case reported by The Indian Express in April 2026, a retired banker, Naresh Malhotra, lost around ₹22.92 crore in a digital arrest scam.
The RBI Ombudsman directed five beneficiary banks to collectively pay him about ₹1.31 crore after deficiencies were found in aspects of their KYC and monitoring of mule accounts.
That decision was based on the specific facts and deficiencies identified in that case. It did not establish a general rule that every bank must repay every digital fraud loss.
The case nevertheless showed how shortcomings in account monitoring can become important when authorities examine a major cyber fraud.
What Should You Do If You Have Lost Money in a Digital Arrest Scam?
If money has already been transferred, act quickly. A fast report may help authorities and banks trace or freeze funds before they move through more accounts.
Step 1: Call the Cybercrime Helpline
Call 1930, India's national cybercrime helpline, as soon as possible after discovering the fraud.
Step 2: File an Online Complaint
Submit a complaint through the official National Cyber Crime Reporting Portal: cybercrime.gov.in.
Keep the complaint acknowledgement number for follow-up.
Step 3: Contact Your Bank Immediately
Tell your bank that the transaction was linked to suspected cyber fraud. Ask it to register a complaint, investigate the transfer and take any permitted steps to hold or trace the funds.
Keep the complaint reference number and copies of your communication.
Step 4: Preserve Evidence
Save bank statements, transaction IDs, UPI details, phone numbers, messages, screenshots and call records that may help investigators.
Do not delete evidence or send more money to the fraudsters.
Step 5: Report the Matter to the Police
Follow the instructions of the cybercrime helpline and local police. Provide the transaction details and complaint reference number.
Step 6: Use the Bank's Grievance Process
If you believe your bank failed to follow the applicable rules, submit a written complaint to the bank and keep its response. You may also explore the RBI's complaint mechanism if the bank's response is unsatisfactory and your case qualifies under the applicable process.
A complaint or investigation does not guarantee recovery, but these steps create a record and may improve the chances of tracing the money.
What If the Bank Says You Approved the Transaction Yourself?
This can make a case more complicated.
Fraud victims may have personally entered a UPI PIN, approved a payment or visited a bank branch while being threatened by scammers. The fact that a transaction was authorised on a device does not, by itself, answer every question about whether the bank met its own obligations.
Investigators may need to examine the circumstances, the account that received the funds, the bank's verification process and whether unusual activity should have triggered additional checks.
Each case will depend on its evidence and the rules that apply. Victims should explain the coercion clearly when reporting the incident.
What Happens Next?
The RBI is expected to provide further details about the proposed KYC Amendment Directions, 2026. The Supreme Court has said it wants to examine the proposed rules and the compensation mechanism.
The next stage will be important because the final framework will need to clarify how bank failures are assessed, how victims can claim compensation and what procedures financial institutions must follow.
Until the rules are finalised and implemented, the exact process and eligibility conditions should not be assumed.
Questions readers ask
Will banks have to refund money lost in digital arrest scams?
The Supreme Court has said the proposed RBI framework should require compensation when a financial institution's failure of due diligence is found to have contributed to the fraud. It is not an automatic refund for every victim.
What did the Supreme Court say on October 29, 2026?
The court said proposed RBI rules should provide compensation of at least the amount lost when a digital arrest or cyber fraud occurs because a financial institution failed to meet its due-diligence responsibilities.
When will the new RBI rules come into effect?
The proposed RBI KYC Amendment Directions, 2026, are expected to be notified by November 30 and implemented by December 31, 2026. The final rules will determine the actual requirements.
What is a digital arrest scam?
It is a fraud in which criminals impersonate law-enforcement or government officials, threaten victims with arrest and pressure them to transfer money.
What should I do if I have lost money in a digital arrest scam?
Call 1930, report the incident at cybercrime.gov.in, contact your bank immediately, preserve transaction evidence and follow the police investigation process.